 Shenzhen HiSpark Ad Media Co., Ltd.
One-line conclusion: Unity is usually described as a game engine company, but its revenue structure says it is an ad-tech company. The engine is the doorway; advertising is the food.
This is not wordplay. It is the only way to explain three things that otherwise look odd: why the engine is free for individual developers, why its earnings react to ad-budget cutbacks faster than the game industry does, and why a single pricing change triggered a revolt across the developer community.
This piece takes Unity apart across ten dimensions: company basics, business model, how the revenue mix evolved, technology, ecosystem, strategy, AI, competition, China, and the non-games business. Every section gives the conclusion first and the evidence second, then lands on what it means for anyone building products.


1. Company basics: three founders in Copenhagen to a NYSE listing
Six milestones in Unity's path
| Stage | Timing | What happened |
|---|---|---|
| Start | 2004 | Three founders set up in Copenhagen with the goal of making game-making simple |
| First product | 2005 | Built a small game on its own engine, then licensed the engine out |
| Mobile boom | Around 2010 | Caught the iOS and Android explosion and became the default for indie developers thanks to build once, ship everywhere |
| Scale-up | 2015 to 2019 | Expanded from the engine into advertising, analytics and cloud services; the product line ballooned |
| Listing | September 2020 | Listed on the New York Stock Exchange, one of very few engine-led public companies |
| Turn and restructure | 2022 to 2024 | Merged ad platforms, hit the pricing backlash, changed management, reorganised the business lines |
The most striking thing here is the rhythm: ten years doing one thing, then everything at once in five.
From 2004 to 2014 Unity was extremely disciplined. It built an engine and solved one problem: developers should not have to rewrite the same code for every platform. Mobile was exploding and hardware was fragmenting, and whoever absorbed the adaptation work won the developers.
After 2015 the picture changed completely: a listing, acquisitions, advertising and analytics stuffed into the product line. The company went from toolmaker to toolmaker-plus-platform. That shift is the precondition for every argument that follows. Its revenue structure changed, but the outside perception of it did not keep up.
2. Business model: one leg builds tools, one leg moves traffic
This is the first key to understanding Unity. The business is split into two clearly separated parts, and the money comes out of two very different pockets.
| Line of business | What it does | Where the money comes from | Who the customer is | Revenue character |
|---|---|---|---|---|
| Create | Engine, editor, developer tools, professional services | Subscriptions (free for individuals, paid for Pro and Enterprise) | Game and industry developers | Stable, predictable, slow-growing |
| Grow | Ad monetization, user acquisition, analytics | Ad share and buying services | Developers who want their apps to earn | Volatile, large, moves with the ad market |
Revenue mix: the money comes mainly from advertising
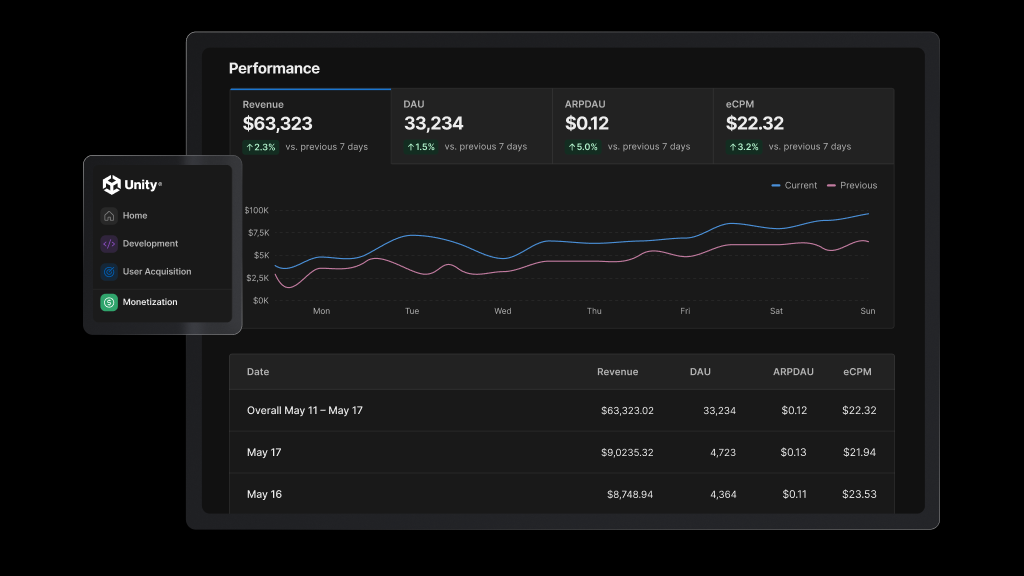
Core judgment: Grow has long contributed the bulk of revenue, close to seventy percent, while engine subscriptions are roughly thirty.
Four consequences follow, and every one of them matters to people building products.
First, a free engine is not generosity, it is a distribution strategy. The engine does not need to make money; its job is to plug developers into the ad ecosystem. A free personal tier buys not revenue but installs and habits, and those two things eventually get monetised on the advertising side.
Second, Unity's earnings behave more like an ad company. They depend on the health of the mobile ad market rather than on the technical merits of an engine release. When advertiser budgets tighten, Unity's numbers react earlier than a pure tools company's.
Third, the free strategy has a price. When the engine does not generate revenue directly, product priorities get squeezed by the monetization business. That is the structural reason developers have long complained that the engine iterates slowly, and it is not purely a capability problem.
Fourth, for developers this changes the bargaining relationship. The tool you use is free, but you may be a customer of its other business line. Seeing that clearly is what lets you judge which requests the platform has an incentive to answer.
3. Three stages of the revenue mix: it became this gradually
Many people assume Unity started as engine plus ads. It did not. This structure is the result of three adjustments across more than a decade.
Three stages of the revenue mix
| Stage | Rough shape | What drove it | What it meant for developers |
|---|---|---|---|
| Tools-led | Engine licensing and subscriptions were the main revenue | Mobile exploded and tools were scarce | Platform and developer interests aligned: build a good tool and people buy it |
| Transition | Subscriptions and ads ran in parallel, ads growing faster | Mobile game monetization matured and ad budgets poured in | The first signs of free tools, paid traffic appeared |
| After platformisation | Ad monetization became the main revenue | M&A plus growth in the mobile ad market | Developers were both tool users and suppliers into the monetization chain |
The point of these three stages: almost every argument about Unity today traces back to the second turn. A tools company and a platform company facing the same users have a natural tension. Tools want users to go deep; platforms want users to spend more. The two usually agree, but they diverge on pricing, data ownership and revenue share.
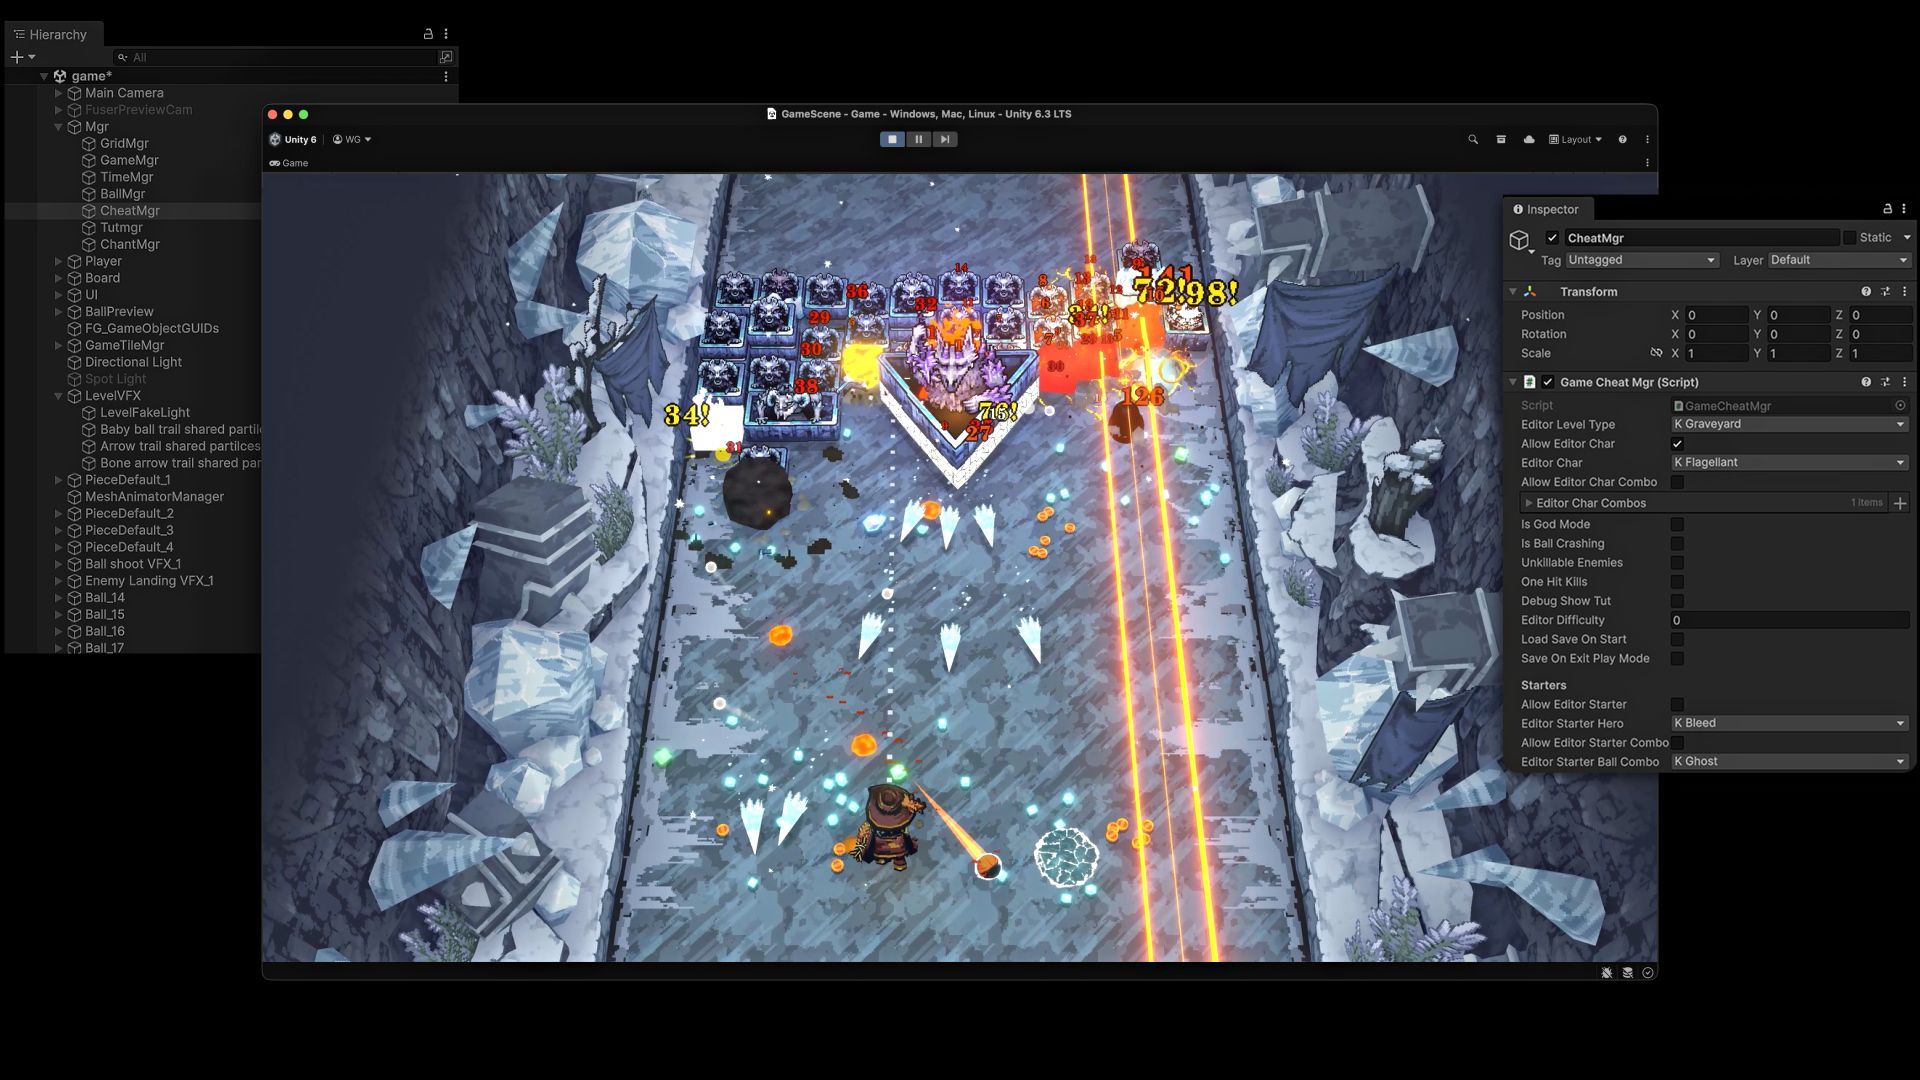
4. Technology: the moat is cross-platform reach, not visual fidelity
Unity is often compared with Unreal on graphics, which is the wrong axis.
| Dimension | Where Unity is strong | Where it is weaker |
|---|---|---|
| Platform coverage | Mobile, console, desktop, web, XR and in-car systems, almost everything | - |
| Learning curve | Friendly syntax, plenty of material, good for indies and small teams | Weaker engineering guardrails on large projects |
| Rendering | Programmable render pipelines covering both lightweight and high-fidelity routes | Top-tier AAA visuals still benchmark against Unreal |
| Efficiency for small teams | Large ecosystem and templates, prototypes come together fast | Deep customisation needs stronger in-house capability |
| Beyond games | Many deployments in car HMI, virtual production and industrial simulation | Still a supporting player next to professional industrial software |
The takeaway: Unity's moat is coverage multiplied by low ramp-up cost, not a ceiling on visuals.
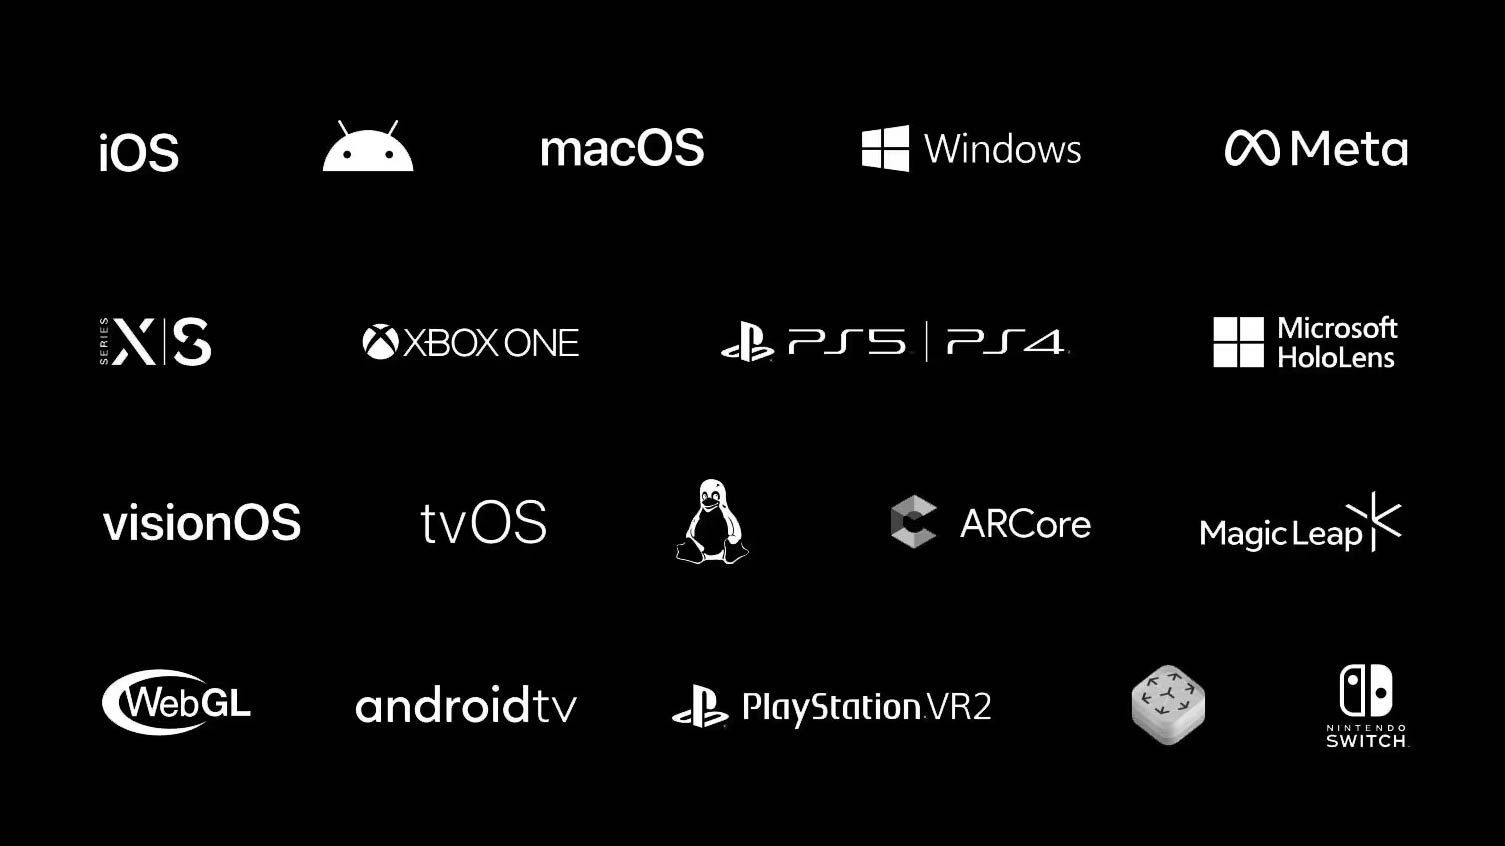
It chose the wider road rather than the higher one. The technical substance of that road is not any single metric but the cost of adaptation: every extra platform, hardware set and OS version makes the everywhere-runs ability more expensive to maintain. A newcomer does not have to close one technology gap, it has to close a whole coverage matrix. That is why challengers usually enter from light scenarios rather than replacing Unity head-on.
A word on the rendering decision: Unity ships two programmable render pipelines, one for lightweight mobile and low-power devices, one for high-fidelity desktop and console. That design is the strategy in miniature. It does not chase a single extreme; it tries to give teams of every size a workable path.
5. Ecosystem: the Asset Store is the most underrated asset
Unity's real stickiness comes from three things, and their value compounds.
Three layers of the ecosystem, each harder to replace than the last
Layer one, the tool itself. The engine, the editor, the debugging and build chain. This layer only holds people by being good to use, and a replacement can appear at any time.
Layer two, the asset store. Assets, plugins and toolkits form a secondary market where developers buy other people's wheels and sell their own. The value here is that it makes time purchasable. A tiny team can buy several months of somebody else's work for a few hundred dollars, and that is the hardest thing to give up when switching engines.
Layer three, the talent and knowledge market. Tutorials, documentation, community answers, skill tags in job listings. When the job ads in an industry say familiar with Unity, and when a newcomer's first stop is a Unity tutorial, the moat has moved from technology into the social layer.
The value of an ecosystem is not direct revenue, it is exit cost. When a team's workflow, asset library and hiring standards are all built around one engine, switching becomes prohibitively expensive. That is Unity's hardest advantage against newer engines, and the reason an open-source engine cannot take it down simply by being free: free solves licensing cost, not the cost of rebuilding talent and experience.
6. Strategy: two acquisitions and one expensive pricing mistake
6.1Two acquisitions that changed the company's identity
| Direction | Strategic intent | Consequence |
|---|---|---|
| A visual effects company | Fold film-grade production into the real-time pipeline and chase growth outside games | Strengthened the technical story for virtual production and similar scenarios |
| An ad platform | Control the monetization step directly, extending from tools into traffic | Rewrote the revenue structure and changed what the company is |
The second acquisition was the watershed. It turned Unity from someone who sells tools into someone who distributes traffic, and put it in the competitive set of ad platforms. From that point its rivals were not only engine companies but the entire mobile advertising industry.
6.2One pricing mistake and the three lessons it left
In 2023 Unity announced that it would charge developers per install. The policy triggered a fierce backlash in the developer community, went through several revisions and was eventually cancelled, alongside management changes and a reorganisation.
The value of the episode is not who was right. It is that it demonstrated three boundaries for platform companies.
Lesson one: you can change the price, not the base unit of billing. Moving billing from seats per year to user volume transfers the platform's cost risk onto developers, and user volume is a variable developers do not control.
Lesson two: free is both a promise and a liability. Installs bought by years of free access become resistance to any pricing change. A free strategy is fine, but it has to be consistent with the business model, and if you pivot you had better be ready for the backlash.
Lesson three: developers spread faster than you expect. Once a community has a shared workflow and identity, its reaction to a policy change is not item-by-item evaluation but collective pushback.
For anyone building a platform, this case study is worth more than any success story.
7. AI: Google and Unity team up on "make a game with one sentence"
San Francisco, 7 October 2026. Google and Unity announced a strategic partnership to build an integrated gaming platform together, which the companies say will launch later this year. In one sentence: put Google's AI, the reach of Google's billion-user products, and Unity's game-building expertise into the same product, so that millions of new creators can make their first game.
That is not just a press line. It maps onto two concrete products.
| Dimension | Google Playground | Unity Spark |
|---|---|---|
| What it is | Google's experimental platform: generate and customise playable games from natural-language prompts, no coding required | A more advanced creation platform wired into Playground, which the company describes as built from the ground up for a new generation of creators |
| Who it is for | People with an idea and no technical background (the company labels it 18+) | Creators moving from something playable to something publishable |
| Current status | The company says it opened the day of the announcement | Closed beta |
| Capability | Prompt-based generation and customisation | Professional-grade mechanics plus high-fidelity 3D plus the Unity runtime |
| How it spreads | Sign in with a Google Play Games profile, with leaderboards, matchmaking and community features built in | Google highlights strong work across its product network and points people towards Spark |
From one sentence to a publishable game: this is a funnel
Core judgment: this is not Unity doing AI. This is Unity grabbing the doorway.
Spark's official tagline is Prompt it. Perfect it. Publish it. Of those three verbs, the one that gives the game away is the middle one. If one sentence produced a finished game, the editor would have no reason to exist. Yet the company defines Spark as an AI game maker with a real editor, and notes that the games use assets created by human artists.
That says two things. First, generating and finishing remain different jobs: a prompt solves the cold start, not the quality bar. Second, the position Unity wants is the road between one sentence and a professional editor, because that is where a user makes their first game and also where they first learn to use Unity.
What it means for the business model (the following is opinion):
First, it does not change the revenue structure, it widens the doorway. As earlier chapters showed, Unity's money comes mainly from advertising rather than engine subscriptions, and the engine's job is to feed developers into the ecosystem. Spark widens the mouth of that funnel from people who can write code to people who have an idea.
Second, it carries the ecosystem moat into the AI era. Chapter 5 showed that Unity's hardest asset is not the engine but the talent and knowledge market. Whoever is a newcomer's first tool gets the default choice for the next decade. That is the bet Spark is making.
Third, distribution was handed to Google, and that is the most valuable part of the deal. Google has a billion-user product network and ready-made accounts, leaderboards, matchmaking and community infrastructure. For an individual creator, whether anyone plays the thing is often more fatal than whether it can be built at all.
What it means for us:
- No need to panic in the short term, but the entry bar must be re-priced in the long term. AI will not replace game developers tomorrow, but it will change who can enter this industry and what the talent structure looks like.
- Three signals worth watching: when Spark moves from closed beta to general availability; how the intellectual property, commercial use and revenue share terms are set for generated content and assets; and whether monetization routes back into Unity's ad system.
- For product people: the prompt box is becoming the new search box. The interface through which users express what they want has changed, and whoever owns that interface gets the next cohort of creators.
The one-line landing: the last cycle of engine competition was about whose visuals were better. This cycle is about who lets people who cannot make games make their first one.
8. Competition: three kinds of rivals, three different fights
| Rival type | Examples | How they compete | Threat to Unity |
|---|---|---|---|
| High-end engines | Unreal | Set the benchmark with visuals and AAA projects, then push downmarket | Splits off mid-to-high-end projects |
| Lightweight engines | Godot | Open source, free, community driven, no licensing cost | Splits off indies and cost-sensitive teams |
| In-house engines | Large studios building their own | Internalise everything through sheer scale | Loses big clients and the reference value they carry |
| Ad-side rivals | Mobile ad platforms | Compete for the same developers' monetization budget | Hits Grow directly |
Four fronts: the rivals are fighting different wars
The real pressure comes from both ends: capped on quality by high-end engines, undercut on cost by open-source engines, and fought over on the ad side by platforms in the same business.
What matters is that these four rivals are fighting different wars. Unreal fights for the narrative of technical ceilings, Godot for cost and freedom, in-house engines for scale effects, and ad platforms for the developers' monetization budget. Unity stands on all four fronts at once, but the one it can least afford to lose is the third. Once a top-tier project succeeds in-house, what is lost is not one client but the most persuasive reference of all: everybody big uses this.
9. China: Unity China as a separately operated joint venture
In China, Unity runs through a joint venture operating independently: local internet and game companies hold equity, a local team runs product and sales, and a localised version and services are offered to domestic developers.
That structure has two practical consequences.
First, compliance and localisation responsibility sit in-market. Handing the China business to a party that knows local rules better is the standard answer for multinational tool companies on data, payments and content compliance.
Second, the technology stack may not stay in sync with the global release. For domestic teams this means do not assume that a feature in the global documentation exists in the local branch, and do not assume the upgrade cadence matches. Confirming which branch you are on, which support channel you use and what your upgrade window looks like before you start will save a lot of debugging time.
10. Beyond games: the real second curve
Outside games, Unity's most concrete deployments fall into three areas.
Three deployments beyond games
| Scenario | What it does | Why real-time rendering matters | Barriers |
|---|---|---|---|
| Automotive | In-car human-machine interfaces, dashboards, 3D interaction | Carmakers need interface and visual capability they can iterate quickly | Long automotive qualification, high certification cost |
| Film and virtual production | Real-time previsualisation, virtual backgrounds, effects work | Moves post-production onto the set and saves reshoots | Deeply coupled to professional film pipelines |
| Industry and training | Digital twins, simulation, operator training | Visualisation lowers training and debugging cost | Requires data integration with industry software |
This line matters strategically more than it matters to revenue. It turns an engine from a tool for the games industry into underlying infrastructure for real-time 3D content in general. The price is that Unity now competes head-on with professional software in several industries rather than harvesting its own turf. Automotive clients are more conservative than game developers, and their procurement cycles are longer.
11. What it means for us: six questions for engine selection
Here is the Unity case distilled into a table you can actually use.
| Question | How to ask it | Unity's answer |
|---|---|---|
| Cross-platform need | Do you need one build across many platforms? | A strength, the broadest coverage |
| Team size | Can you absorb heavy engineering? | Better suited to small and mid-sized teams |
| Visual ceiling | What tier of visual quality is the project aiming at? | Mid-to-high is fine; for the very top look elsewhere |
| Monetization dependence | Will advertising be a main revenue line? | Naturally aligned with its ad system |
| Migration cost | Whose ecosystem is your workflow bound to? | Once bound, migration is extremely expensive |
| Long-term risk | Could a platform policy change hurt me? | The 2023 episode says keep a fallback |
The last two rows matter most: engine selection is not a technology question, it is a question of where your team's assets live. What you bind to is never just the engine, but the asset library, the talent profile and the working habits. And the platform's policy changes are the part of the risk you cannot negotiate.
12. Summary
- Identity: Unity is a tools-plus-ads composite, and most of the revenue comes from advertising rather than engine subscriptions.
- Structure: today's shape is the result of three adjustments, and nearly every controversy traces back to the step from toolmaker to platform.
- Technology: the moat is cross-platform coverage and a low ramp-up cost, not a visuals ceiling.
- Ecosystem: the asset store and the talent market form the real migration barrier, harder to break than free pricing.
- Lessons: the 2023 pricing backlash proved a platform can change its prices but not the base unit of billing.
- AI: the Google partnership turns where newcomers make their first game into the new battleground; the fight is moving from visuals to the doorway.
A four-way comparison of Unity, Unreal, Godot and in-house engines, plus selection advice by team size and a checklist for aligning engine choice with monetization.
What is inside:
- A four-way comparison of Unity, Unreal, Godot and in-house engines
- Selection advice by team size and project type
- A checklist for aligning engine choice with monetization on overseas products
If you are weighing up an engine choice, or want to talk through a product's monetization architecture, leave a comment.