 Shenzhen HiSpark Ad Media Co., Ltd.
One-line conclusion: Taboola is not an ad company, it is a traffic wholesaler. It buys cheap traffic from publishers, processes it into high-intent traffic, and retails that intent to advertisers. The spread in the middle is the business.
That single judgment explains three things: why revenue looks huge but margins are not, why it must keep signing bigger publishers, and why it and its main rival eventually became one company.
This piece breaks Taboola down across nine dimensions: company basics, business model, revenue and cost structure, product matrix, M&A and competition, how the industry is shifting, the risk surface, what it means for anyone in the traffic business, and a short summary.


1. Company basics: from a recommendation widget to a Nasdaq listing
| Stage | Timing | What happened |
|---|---|---|
| Start | Around 2007 | Founded in Israel, going after the slot nobody wanted: the recommendation strip at the bottom of an article |
| Scale-up | 2012 to 2019 | Signed up mainstream media at volume; the recommendation strip became standard publisher furniture |
| Listing | 2021 | Went public on Nasdaq through a merger |
| Consolidation | 2024 to 2025 | Merged with its main competitor, turning a duopoly into a single dominant player |
Four milestones in Taboola's path
The takeaway: Taboola started as position arbitrage. Advertisers looked down on that strip at the bottom of a mainstream media page. But the traffic was real and the cost was tiny. Whoever industrialised that slot first owned it.
2. Business model: buy traffic wholesale, sell intent retail
| Step | Who is involved | How the money moves |
|---|---|---|
| Supply | Publishers (media sites) | The platform shares most ad revenue back to the publisher |
| Processing | The platform itself | Recommendation algorithms turn idle browsing into plausible interest |
| Demand | Advertisers, mostly performance | Pay per click or per conversion |
Where the money goes: most of it back to publishers
Core judgment: the margin in this business is set by the cost of buying traffic, not by the technology.
Most of what advertisers pay goes back to publishers. Two things follow.
First, scale is not optional. Without enough publishers you cannot buy traffic cheaply enough; without enough traffic you cannot afford the algorithm and the sales team. This is a classic two-sided scale game.
Second, the moat is exclusive supply. Whoever signs exclusive or long-term deals with top-tier media holds the scarce resource. That is harder to catch up with than an algorithm lead.
3. Revenue and cost structure: a business model that is easy to misread
| Metric | Character | What it means |
|---|---|---|
| Gross revenue | Large | The total advertisers spend |
| Traffic acquisition cost | A high share, usually more than half | The part shared back to publishers |
| Net revenue | Gross revenue minus traffic cost | The only number comparable to your own costs |
| R&D and sales | A meaningful share of net revenue | The spend on algorithms and client relationships |
Read net revenue first
When you read Taboola's filings, the first number to look at is net revenue, not gross revenue. Counting the publisher's share as revenue makes the company look far bigger than it is. This accounting habit runs through the whole native advertising industry.
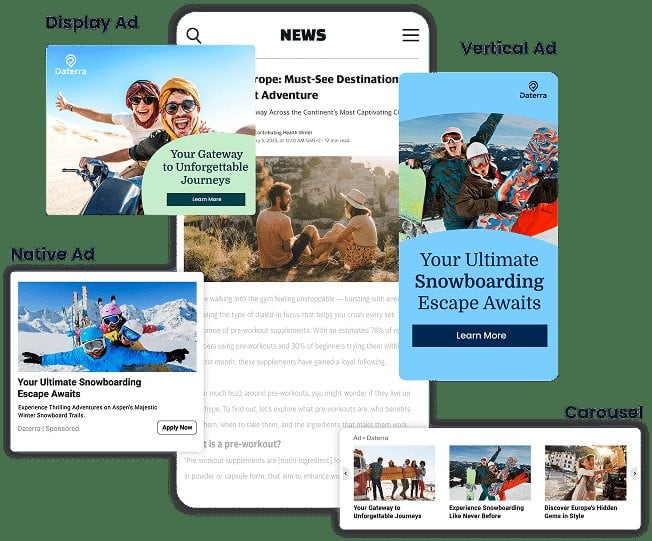
4. Product matrix: from recommendation slots to a full performance stack
| Product line | For | What it does |
|---|---|---|
| Content recommendations | Publishers | Turns page bottoms into monetisable inventory |
| Performance platform | Advertisers | Buys on clicks and conversions |
| Commerce placements | E-commerce advertisers | Puts products directly into the recommendation strip |
| Data and measurement | Advertisers | Attribution and optimisation tools |
The direction of travel is clear, and in the last two years it has accelerated into three specific products.
Realize is the performance platform the company now leads with, positioned explicitly for advertisers who want to scale beyond search and social. On top of it sits Realize+, described as an agentic system that turns advertiser goals into outcomes: it reads signals, makes decisions and adapts in real time rather than waiting for a human to tune a campaign.
DeeperDive points the other way, at publishers. It turns a site's own archive into a conversational AI layer that answers reader questions using only that publisher's verified journalism, and the company says it drives a 15% click-through rate from every AI answer back to the publisher's content. The pitch is blunt: the internet was built to be explored, not summarised.
Put together, the product line has moved from selling a slot, to selling an outcome, to selling a closed loop. When a platform controls both the traffic entry point and the conversion data, its pricing power rises sharply.
5. M&A and competition: an industry down to two players, then to one
In 2019 and 2020 the two biggest players tried to merge and failed. In 2024 and 2025 the same merger was pushed through, and this time it closed.
The repetition says one thing: native advertising has very strong scale effects and very weak differentiation. When two companies look almost identical to both advertisers and publishers, merging is the only efficient answer, because it removes duplicated sales costs and duplicated bidding for the same inventory.
What this means for outbound teams: if the players in a category have no product difference and only a scale difference, the end state is acquisition. Judging that early keeps you from over-investing in the wrong lane.
6. The shifting board: three sides compressing the business
| Pressure | Mechanism | Effect on the platform |
|---|---|---|
| Platforms (browsers and operating systems) | Tighter privacy rules, the end of third-party cookies | Weaker targeting, lower conversion efficiency |
| Publishers building their own | Media houses run their own recommendations and inventory | Less high-quality inventory available to buy |
| Short video and social | Taking user time | Total traffic to article pages declines |
Three pressures squeezing the category at once
All three pressures act at once, so the ceiling is squeezed from three directions. That is why the leading platforms have re-centred on commerce and AI optimisation over the past few years. It is not a search for growth, it is a search for a way out. Realize is the attempt to take performance budgets away from search and social; DeeperDive is the attempt to make publishers stickier so they keep supplying the platform.
7. Risk: three fragile points
One, supply concentration. Top publishers account for a meaningful share of revenue, so losing any single large client shows up directly in the numbers.
Two, traffic-quality disputes. Recommendation strips have long been accused of hosting low-quality content and clickbait. That is both a regulatory risk and the reason brand advertisers hesitate to move budget in at scale.
Three, the intermediary being disintermediated. Once publishers learn to run recommendations themselves and advertisers learn to buy traffic directly, the value of the middle layer gets squeezed.
8. What it means for us: three things to watch in a traffic business
| Question | How to ask it | Taboola's answer |
|---|---|---|
| Nature of the business | Are we earning a spread or a technology premium? | A spread. Scale decides whether you live |
| Key resource | Who holds the scarce supply? | Exclusive deals with top publishers |
| Cost structure | Who gets the biggest slice? | Publishers. Net revenue is the real size |
| Ceiling | Who is pressing down? | Platform policy, publisher self-build, short video |
| Way out | Where does it go next? | Commerce loops and AI optimisation |
The most important row: every buy-wholesale-sell-retail business eventually has to answer why it can get supply that nobody else can.
9. Summary
- Identity: Taboola is a traffic wholesaler earning a spread on processing and matching traffic.
- Structure: gross revenue flatters it; net revenue is the real size.
- Landscape: differentiation is thin, so the industry drifts towards consolidation.
- Risk: supply concentration, traffic-quality disputes and disintermediation are the three long-term fragile points.
A three-column template for gross revenue, net revenue and traffic cost, plus a moat checklist.
What is inside:
- A three-column template for gross revenue, net revenue and traffic cost
- A checklist for judging the moat of a traffic business
- A self-check list for the monetization architecture of an overseas product